Most accounts I audited had the wrong bid goal. Not slightly wrong. Wrong enough to quietly burn 20% to 30% of profit for months while the report still looked green.
I used to tell clients CPA and ROAS were mostly a preference. I was wrong. CPA tells Google to buy conversions at a fixed price; ROAS tells it to buy revenue at a ratio. Pick the wrong one, and you train the machine to do the wrong job, then pay it to keep doing it. At $20k a month in spend, that mistake compounds fast.
What CPA and ROAS actually optimize
Target CPA is simple. You tell Google: get me a conversion for $60. Google bids higher in auctions it thinks can produce that conversion for $60 or less, then bids lower or skips auctions it expects to cost more.
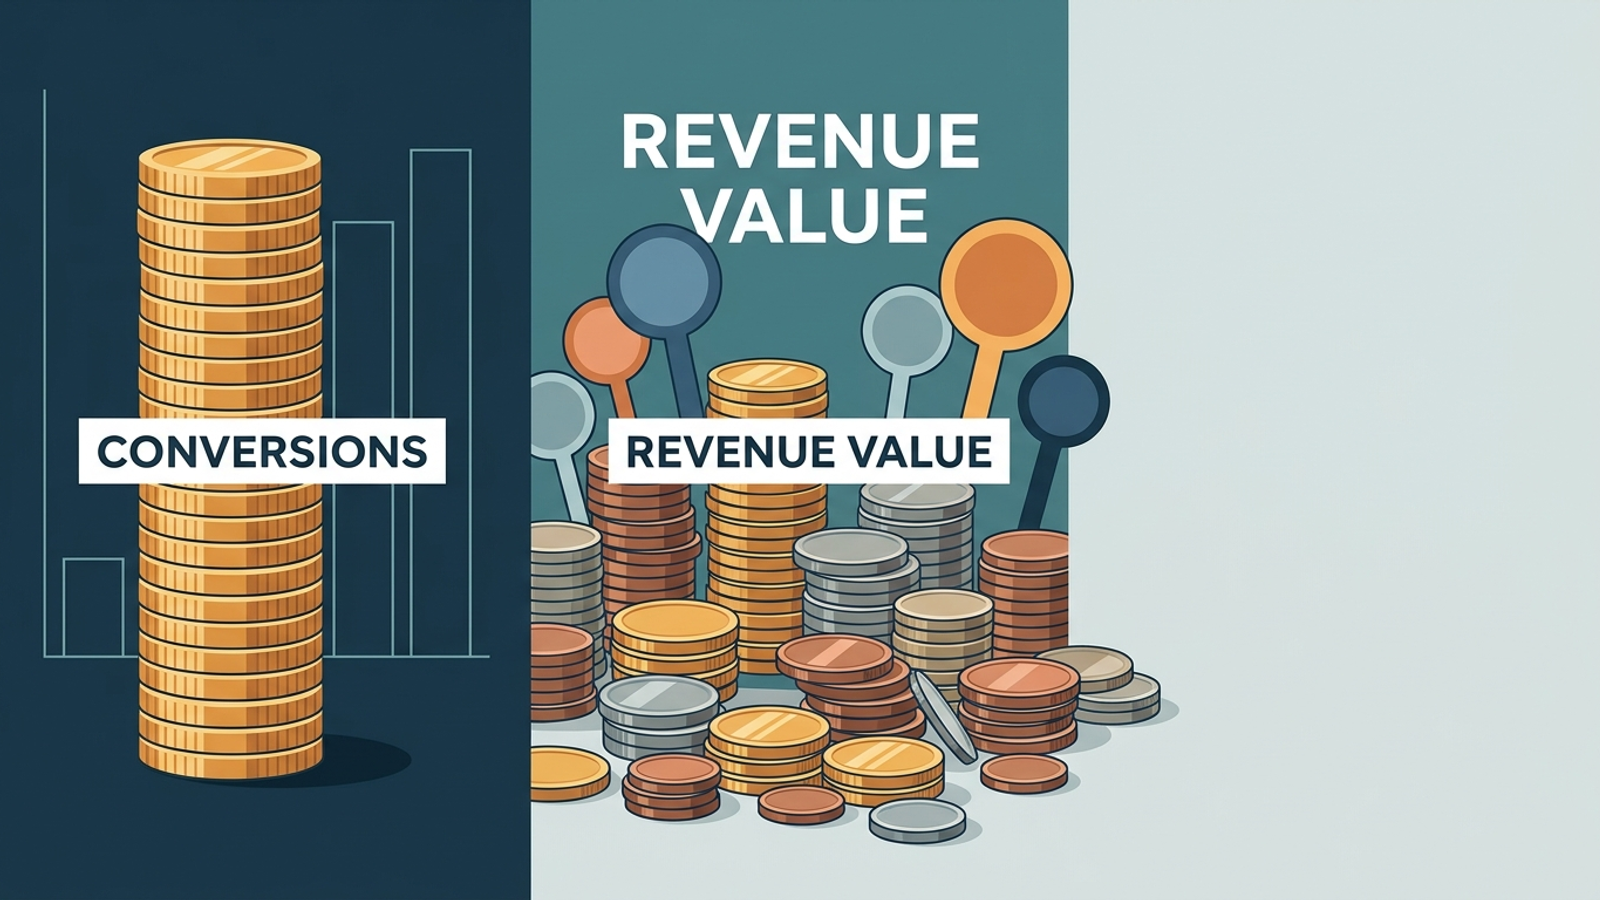
The math is cost divided by conversions. It does not care whether one conversion is worth $50 and the next is worth $500. A conversion is a conversion.
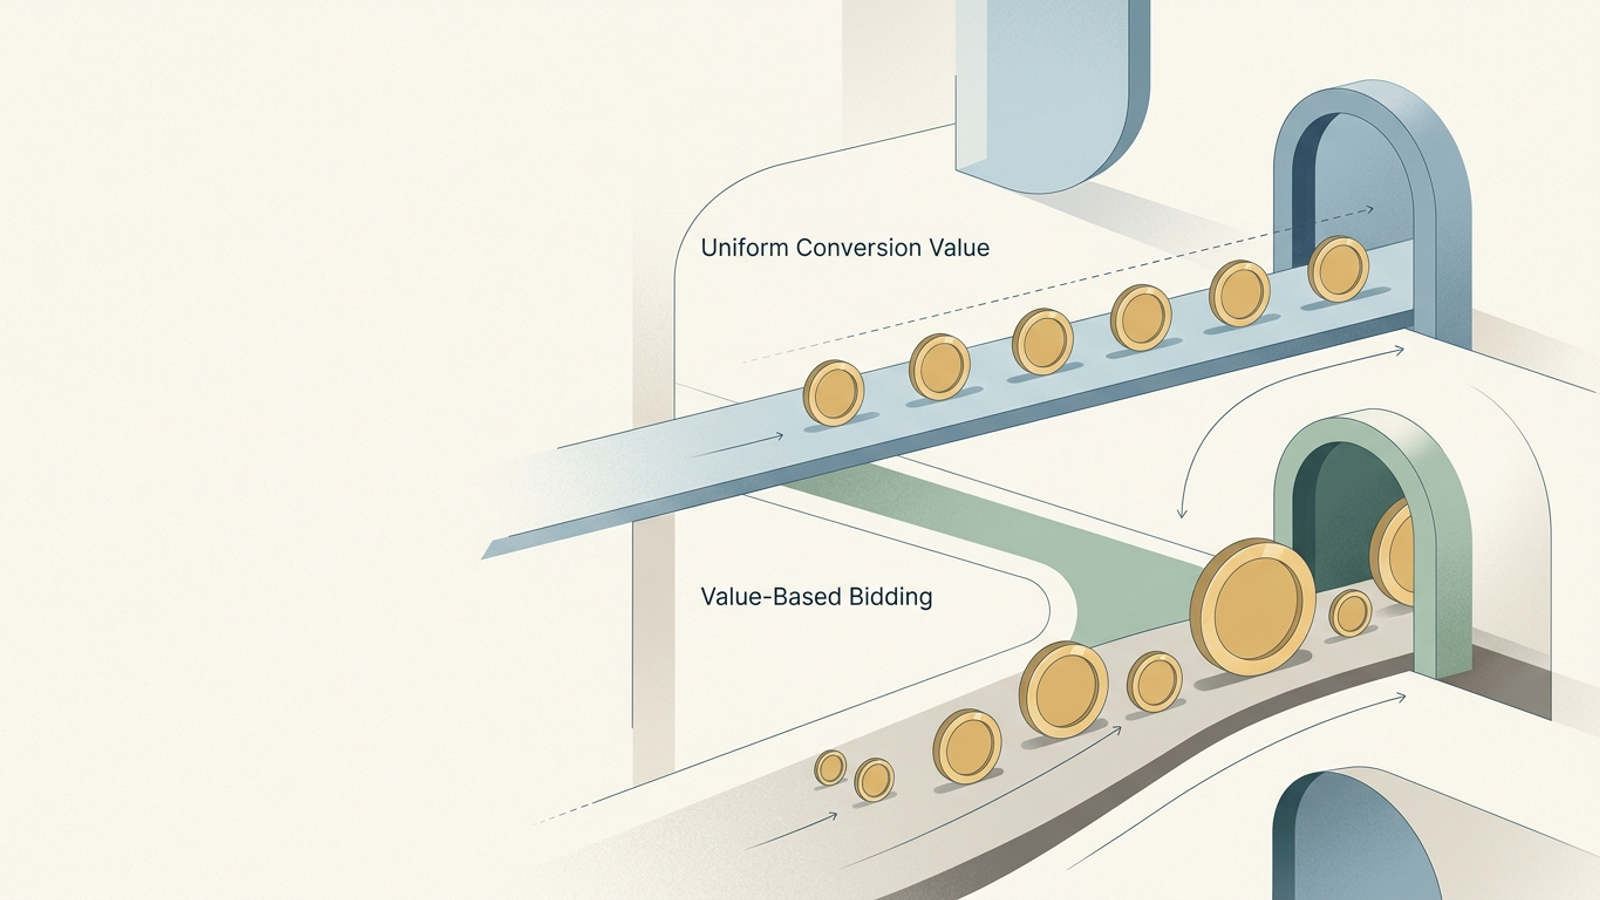
Target ROAS is pickier. You tell Google: for every $1 I spend, bring me back $4 in conversion value. That is 400% ROAS. Google then bids on predicted value, not just predicted conversion rate.
The math is conversion value divided by cost. A $500 order can earn a bigger bid than a $50 order even when both people are equally likely to convert.
That difference is the whole decision:
- Use CPA when each conversion is worth roughly the same amount.
- Use ROAS when conversion values vary widely and bidding needs to respect that spread.
The bid goal should match the economics, not the sophistication of the dashboard.
Use ROAS when order value changes the answer
Run a store where one order is $28 and the next is $1,400, and CPA bidding will lie to you. It treats both checkouts as equal wins. It can happily buy ten cheap sales while skipping the expensive one that actually pays rent.
ROAS bidding fixes that by predicting value on each auction, bidding higher when the predicted cart is large and lower when it is not. That is the mechanism. Google describes value bidding in much the same way: it analyzes predicted value per search and adjusts bids to maximize return on that search.
I learned this on a home-goods account with $35 accessories sitting next to $1,800 sofas. CPA looked great. Profit did not.
ROAS only works when you feed it the truth. You need to set values for the conversions you track before Google will let you use it. For Search and Shopping, you also need at least 15 conversions in the past 30 days at the conversion-tracking level.
Here is the practical rule:
- If cart values span more than 3x from low to high, ROAS is usually the better fit.
- If margins vary sharply by product, ROAS gives the system a reason to favor the better sale.
- Pass through real revenue, ideally revenue after returns, rather than a made-up flat value.
No usable values means no usable ROAS. It is that simple.
Use CPA when a lead is basically a lead
CPA wins when one lead is one lead. Think home services, legal intake, dental implants, or SaaS demo requests. A booked call may be worth roughly the same whether it came from “emergency plumber near me” at 2 a.m. or “drain cleaning quote” at noon.
There is no reason to have Google price those auctions around predicted revenue if the value is effectively flat. You want volume at a price your economics can support, and CPA is built for exactly that.
Google frames the data requirement similarly: Smart Bidding needs at least 30 conversions over a longer window to judge results, and 50 for Target ROAS. CPA is the lighter lift.
I ran a garage-door account at $45 per call for two years on Target CPA. Same offer. Same service area. Close rates stayed stable. Switching to ROAS would have added complexity with zero upside because there was no meaningful value spread to optimize.
This will not work for everyone. Skip CPA when your leads close at wildly different rates. If enterprise demos close at 22% and SMB trials close at 3%, but you feed both to Google as equal $80 conversions, CPA will chase cheap SMB volume and starve the pipeline that actually closes.
Before setting a target, clean up the conversion action:
- Choose one primary action for the bidding goal.
- Turn duplicate conversions off.
- Filter junk leads and broken tracking events.
- Move supporting actions, such as newsletter signups, to Secondary.
If you cannot trust the conversion, the target is fiction.
A four-question framework for choosing the goal
I run every account through the same four questions, in order. Cause comes first, then the bid goal. Skip that order and you choose what sounds sophisticated instead of what your data can support.
-
Do conversions vary in value by 3x or more?
If yes, and you can track that value back to the click, use ROAS. If every lead or sale pays about the same, use CPA.
-
Do you have enough recent history?
With fewer than 30 conversions in 30 days, stay on Max Conversions without a target until you have more data, then set CPA. With fewer than 50 conversions carrying values, do not set ROAS yet. Google will still spend; it just will not have much of a value pattern to learn.
-
Can you pass real value back to Google?
Ecommerce purchases with order values and refunds handled: yes. Lead generation with imported offline close data: yes, and ROAS starts making sense. Raw form fills only: no. Stay on CPA.
-
Do margins differ by product or service line?
If they do, use ROAS targets by campaign or value rules that weight high-margin actions more heavily. One blended target across mixed margins trains the system to chase cheap revenue.
Write down the answers before touching the settings. Most bad switches fail on question two or three, not on bid math.
Switch from CPA to ROAS without resetting the account
Flipping from CPA to ROAS in one click is how a good campaign goes quiet for two weeks. I switch in stages.
- Keep the campaign on Target CPA first. Start reporting a value for every relevant conversion without changing the bidding goal.
- Let value data accumulate. Run for four weeks or one to two conversion cycles, whichever is longer. Google gives the same guidance in its value-bidding setup material.
- Set the first ROAS target from history. Take the previous four weeks of conversion value divided by cost, excluding the conversion-delay window, and use that result as the starting point.
- Leave it alone long enough to learn. Give the campaign another one to two conversion cycles. Do not change budgets and targets in the same window.
- Tighten gradually. Move in 10% to 15% steps only after the campaign settles.
That waiting period feels slow. It is cheaper than rebuilding learning around bad data.
If the account cannot afford a wobble, run the change as a campaign experiment instead of editing the live campaign.
Start at historical ROAS, not aspirational ROAS. A 400% campaign does not become a 600% campaign because you typed 600. It becomes a low-volume campaign.
The mistakes that make both goals look broken
Most ROAS failures I see are not bidding failures. They are target failures.
Someone reads that 500% ROAS is good, types 500 into a campaign running at 320%, and volume falls off a cliff four days later. Smart Bidding can only hit that new target by skipping auctions that do not clear it. Set the bar 50% above history and you just told the system to skip many of the auctions that used to make you money.
CPA fails the same way in reverse. A lead-gen account pays $90 per qualified call, but finance wants $50, so someone sets a $50 target. Calls dry up. Then the team concludes CPA bidding does not work.
It worked. It did what you asked.
The second killer is mixed math. You need one clean primary conversion action per bidding goal, with clean values. I still find Target CPA accounts optimizing toward a bucket that includes form fills, phone calls, newsletter signups, and a broken thank-you page firing twice.
Google counts four conversions at $25 each and reports a $25 CPA. The client counts one real lead at $100.
If your conversion actions lie, your target optimizes the lie. Before debating ROAS versus CPA, open Conversions, choose one money action, and demote the rest to Secondary. That cleanup does more than most target tweaks.
Two $20k examples that make the choice obvious
Say you are spending $20k a month.
Ecommerce: value spread makes ROAS the better control
An ecommerce store gets 400 orders and $80k in revenue. Average order value is $200, but the actual range runs from $30 to $900. Blended CPA is $50.
Set Target CPA at $50, and Google chases $50 checkouts while treating a $900 sofa buyer exactly like a $30 cable buyer. Move to 400% ROAS, calculated as $80k divided by $20k, and Google can pay more for sofa auctions while backing off cable auctions.
Same budget. Richer mix.
I have watched that shift lift profit 18% to 24% in six weeks without another dollar of spend. The cause changed first: bids followed predicted value, then revenue followed bids.
When revenue per order varies, make the bidding follow revenue.
Lead generation: flat expected value makes CPA cleaner
Now take lead generation. Same $20k. You get 250 calls at $80 each, a 20% close rate, and an average job worth $1,200. Every call has an expected revenue value of about $240.
There is no spread worth pricing. CPA is the cleaner control. Set an $80 Target CPA and let Google buy calls.
If you forced 300% ROAS on raw calls with every call valued at $1, you would be asking Google to optimize noise. What the deck might call “value-based strategy,” I call assigning the same pretend number to everything.
If you can tie real job revenue back through offline conversion import, ROAS becomes fair game again. Until then, CPA keeps the math honest.
Know when to switch back to CPA
I switch ROAS back to CPA when the value signal thins out: seasonal catalog turnover, tracking breaks after a site migration, or volume drops below that 50-conversion line.
The mechanism is straightforward. Without fresh value examples, ROAS bidding guesses. CPA guessing on conversion rate is safer than ROAS guessing on revenue.
I made this call on a lead-gen account after offline import broke for three weeks. ROAS kept spending toward stale values. Back on CPA at the last proven $80 target, cost per qualified call settled in nine days.
If you cannot trust this month’s values, do not bid on them.
This is the part I no longer do by hand at 1 a.m.: watching value spread, resetting targets in 10% steps, and catching the thank-you page that double-fires. That is machine work. It needs to run every hour, not at the next monthly check-in.
That is why I run accounts on groas now. The engine holds the target, logs bid and budget moves with reasoning, and a named strategist owns the guardrails while I own the economics.
Flat-value volume at a price you can afford means CPA. Mixed-value revenue at a ratio that protects margin means ROAS. Set the first target from your own last four weeks, move it in small steps, and fix the conversion action before blaming the algorithm.
Most agencies will not tell you this part because the monthly check-in model needs the goal to look complicated. It is not. Cause, then effect, then profit.